
ACCOUNTING FOR HOSPITALITY BUSINESSES
Hospitality Accountants for Restaurants, Cafes and Venue Groups
A full venue should leave more than a busy roster. We help established hospitality businesses understand food and wage costs, keep tax and accounts current, and plan the cash needed for the next hire, fit-out or venue.
Ongoing accounting, tax and business advice. Australia-wide.
★★★★★5 out of 5 stars
Chartered Accountant-led
Led by directors Elle Green CA and Simon Burke CA, with the accounting and tax scope agreed for your business.
Meet the accounting team
Xero and useful reporting
Connect the accounting records with takings, payroll and supplier information so the reports explain what the venue earns.
Accounting software and systems
Registered Tax Agent
Business tax services with registered tax-agent responsibilities and a clear scope of work.
TASA disclosure statement
Accounting Consultant of the Year 2025
Elle Green won Accounting Consultant of the Year at the Women in Finance Awards 2025.
See the 2025 results
Meet Elle
FULL TABLES. CLEARER NUMBERS.
Know what the venue keeps after the service is over
Card takings arrive quickly. Rent, wages, suppliers, tax and the next equipment bill compete for that cash. Hospitality accounting needs to connect each part of the operation with the result the owner can actually use.
Understand the margin
Separate food, beverage and labour costs from rent and other overheads. See which changes are affecting the result.
Venue margin and prime cost
Plan the roster financially
Assess the cost of staffing a service, extending trading hours or adding a manager before making the commitment.
Wages and staffing decisions
Reconcile every sales channel
Bring POS sales, merchant settlements, delivery fees and refunds into one reliable accounting picture.
Sales and settlement reconciliation
Protect the next few months
Look ahead to supplier payments, tax, quieter periods and expansion costs, using a forecast that reflects the venue.
Hospitality cash flow forecasting
THE BUSINESS BEHIND THE NUMBERS
Hospitality businesses, with different ways of earning a margin
The same revenue figure can describe very different operations. A cafe, a restaurant and a group of licensed venues need different questions answered before their performance can be compared.
Restaurants
Food and beverage mix, kitchen and front-of-house wages, bookings, cancellations, supplier price changes and delivery sales. We organise the accounts around the information the owner can act on between services.
Cafes and coffee businesses
High transaction volumes, short peak periods, takeaway sales and a roster that has to fit demand. Reporting should show how purchasing, waste, menu changes and opening hours affect the return.
Bars, pubs and licensed venues
Beverage stock, food service, security, entertainment and different trading periods can carry different costs. We agree the accounting scope around the venue; specialist liquor, gaming or excise advice remains a separate engagement.
Takeaway and delivery-led venues
A delivery order can cost more to serve than a counter sale. Platform deductions, refunds, packaging and settlement timing need to be visible before the owner judges the value of that channel.
Catering and event food businesses
Deposits, event dates, casual staffing and ingredients purchased before the final invoice is paid create a different cash cycle. Job or event reporting should connect the quote with the costs actually incurred.
Multiple venues and hospitality groups
Shared staff, purchasing, management costs and related entities can obscure individual venue results. Owners need comparable site reporting alongside the accounts and obligations of each entity.
Who this service is built for
Our ongoing accounting and advisory service is designed for established businesses, generally turning over $400,000 or more, that need reliable accounts and a regular conversation about performance.
A useful fit for ongoing support
- A restaurant, cafe, licensed venue, food-service operation or venue group.
- Staff, regular supplier commitments and decisions that cannot wait until year-end.
- Xero in use, or a willingness to review the accounting set-up.
- An owner who wants visibility over margin, cash and tax commitments.
- A bookkeeper or office team who needs clear coordination with the accountant.
Where the scope needs a different specialist
Tell us if you mainly need a single low-cost individual return, a commercial lease negotiated, employment-law advice or a finance product. We define the accounting work we can deliver and identify where a lawyer, workplace specialist, broker or other adviser should be involved.
What brings an owner to Acctivate Accountants
The first conversation starts with the issue you are trying to resolve.
| What you are noticing | What we examine | Explore |
|---|---|---|
| The venue is busy but there is little left | Food and wage costs, purchasing, waste, pricing and fixed overheads | Venue profitability |
| The POS total does not match the bank | Fees, refunds, settlement timing and delivery-platform deductions | Sales reconciliation |
| The roster keeps getting more expensive | Paid hours, employment on-costs, service demand and management time | Staff costs |
| BAS or a quiet month catches you out | Expected receipts, supplier terms, tax set-asides and upcoming commitments | Cash flow |
| You are considering a second site | Fit-out, deposits, staffing, ramp-up and the effect on the existing venue | Another venue |
| You cannot compare your venues fairly | Consistent reporting definitions, shared costs and inter-entity transactions | Group reporting |
ACCOUNTING AND ADVICE FOR YOUR HOSPITALITY BUSINESS
Accounting services tied to the way a venue operates
The engagement brings compliance and management information together. We agree who prepares the records, how often reporting is needed and which decisions you want help working through.
Business accounts and tax
Financial statements, business tax returns and owner tax work within the agreed engagement. Tax planning looks ahead to the expected position rather than starting with a surprise bill.
GST, BAS and reconciliations
Check sales, expenses and GST records against the underlying activity. Agree the BAS timetable and resolve discrepancies before they become a year-end clean-up.
Management reporting
A clear view of sales, cost of goods, labour and operating expenses, with venue or channel detail where the records support it. Reports should explain a change, not simply display it.
Cash flow forecasting
Expected receipts and payment commitments across wages, suppliers, rent, tax and equipment. Update the forecast when trading assumptions or plans change.
Bookkeeper and payroll coordination
Define who supplies the POS and payroll information, who reconciles it and who checks the final position. Payroll processing and specialist employment advice are scoped explicitly.
Structure and growth advice
Assess another venue, a new partner or an ownership change through the financial and tax questions. Work alongside legal and finance advisers where their expertise is needed.
VENUE PROFITABILITY
What the venue earns after food, drinks and wages
Prime cost brings cost of goods and labour together. It is a useful starting point, but the money left still has to cover rent, utilities, insurance, administration and other overheads before it becomes profit.
Use consistent definitions
Compare like with like. Clarify whether labour includes super and other employment on-costs, how stock usage is calculated, and where delivery fees and packaging sit. A percentage is useful only when the underlying accounts are consistent.
Find the reason a percentage moved
A food-cost increase may come from supplier pricing, portion size, waste, sales mix or a stocktake difference. We use the accounts and operating information together to distinguish those explanations before deciding what to change.
Food, beverage and wastage need their own accounting story
Purchases are not the same as consumption. Stock brought into the venue, stock left at the end of the period, waste and transfers between sites all affect the reported cost of sales.
Purchasing and stock use
Agree stocktake inputs and reporting periods. Reconcile opening stock, purchases and closing stock so one unusually large order does not distort the month.
Menu and sales mix
A higher average sale does not necessarily mean a better margin. Examine the mix of food, beverages, delivery and discounted sales alongside the cost of serving them.
Waste and supplier changes
Connect purchasing price changes and recorded waste to the accounts. Keep operational responsibility for counting, portioning and waste records clear.
Staff costs, rosters and the hours you choose to trade
The wage on a payslip is only part of a shift’s cost. Super, relevant penalties and allowances, leave, workers’ compensation and management time affect the return from each trading period.
Cost the proposed change
Before extending hours or adding a manager, estimate the additional sales and direct costs, then the staffing and overhead commitments the decision creates. Test a quieter trading case as well as the expected result.
Keep payroll responsibilities clear
Venue and payroll teams supply accurate hours, classifications, leave and allowance information. We agree the accounting and payroll work in the engagement. Award coverage and complex employment interpretation need the appropriate workplace expertise.
Use the applicable award
Restaurant, hospitality, fast food and other award coverage depends on the actual business and work performed. A cafe or restaurant should not automatically apply the Hospitality Award simply because it operates in hospitality.
A bank deposit is not the venue's total sales
POS sales, card settlements and delivery-platform payouts describe different parts of the same transaction. Recording only the net deposit can hide revenue, fees and refunds.
We establish a repeatable process for cash takings, merchant settlements, platform fees, tips and refunds. The exact treatment depends on the transaction and records. Differences should be investigated rather than pushed into an unexplained balancing account.
CASH FLOW
Plan for the weeks when sales and commitments pull apart
Hospitality brings frequent receipts and equally frequent spending. A good sales week can still leave the business short when wages, rent, supplier accounts and tax fall due together.
| Forecast item | What it needs to reflect |
|---|---|
| Sales receipts | Trading patterns, booked events, settlement timing and realistic quieter weeks. |
| Staff payments | The actual pay cycle, payroll commitments and super payment timing. |
| Supplier accounts | Payment terms, stock orders, deposits and expected price changes. |
| Fixed commitments | Rent, insurance, utilities, equipment funding and other recurring payments. |
| Tax and owner payments | GST, PAYG, income tax and planned owner remuneration, kept distinct. |
A rolling 13-week forecast makes the timing visible. We test the effect of lower sales, an equipment failure or a delayed opening so the owner can assess the cash buffer needed, adjust a commitment or speak to a finance adviser early.
Can the first venue support a second?
Another lease creates commitments well before the new venue reaches normal trading. The existing site needs enough cash and management capacity to carry that period without weakening its own operation.
Model both venues together
Include the new site’s deposits, fit-out, equipment, opening stock and pre-opening wages. Then test the effect of a slower opening, shared management time and additional debt repayments on the existing business.
Set a decision point before signing
Agree the assumptions, the minimum cash buffer and the performance the second venue would need to reach. Your solicitor advises on the lease; the financial model tests what that commitment would mean.
Compare venues without losing the group picture
One strong venue can mask another that consumes cash. Each site needs comparable reporting, and each legal entity still needs its own accurate accounts and lodgements.
Use the same reporting definitions
Separate revenue, food and beverage costs, labour, occupancy and shared overheads consistently. Record transfers of stock and staff time so site results are not improved simply by moving costs elsewhere.
Reconcile the group
Related-party loans, management charges and transactions between entities must be identified before combining the results. An internal charge is not new external revenue for the group.
GST, BAS and tax planning for hospitality businesses
Tax reporting starts with reliable sales and purchase records. The treatment depends on what is supplied and how it is sold, not only the name of the venue.
Food and beverage GST
Dine-in sales and hot takeaway food are generally taxable. Other food and beverage supplies need their own assessment. We check the relevant treatment and POS coding rather than assuming every menu item has the same rule.
Choose the right reporting rhythm
Your BAS obligations depend on the business’s circumstances. A monthly BAS does not itself produce accurate monthly management accounts. Reporting still needs stock, wages, reconciliations and adjustments appropriate to the period.
Plan tax while decisions can still change
Review forecast profit, PAYG instalments, owner remuneration and planned equipment purchases during the year. Consider the cash cost alongside the tax effect before accelerating spending.
Structure the business around ownership and future commitments
A sole trader, company or trust changes how the business is operated and taxed, how owners receive money and what administration is required. A structure should be assessed against the actual venue, owners and plans.
Owners and remuneration
Clarify how owners are paid, how tax is set aside and how drawings or related-party loans are recorded. Business cash and an owner’s personal spending are separate questions.
Another partner or venue
Assess the accounting and tax consequences before changing ownership, introducing a partner or creating another entity. Legal documentation needs its own advice.
Assets and related entities
Separate entities may have different roles, but moving assets or setting up hire arrangements has tax, legal and financing consequences. Review the full arrangement before making transfers.
Xero, POS records and reports that an owner can use
The system should reduce uncertainty about sales, costs and cash. Adding a connection is only useful if the data arrives correctly and someone is responsible for checking it.
Start with the records you already have
Review the Xero file, chart of accounts, POS and merchant reports, delivery settlements, payroll exports and supplier records. Agree what can connect directly and what needs a controlled import or reconciliation.
Build reporting around the decisions
Venue, food and beverage, labour and channel reporting depend on consistent source data. We define the level of detail the records can support and avoid presenting an estimated split as an exact result.
Make the handover practical
Your venue or bookkeeping team continues to own the agreed daily inputs. Acctivate checks the accounting, prepares the reporting and discusses the implications within the engagement. Additional receipt-capture or reporting tools are selected for the work required.
What useful hospitality reporting should answer
The report needs to lead to a decision. The exact pack and review frequency are agreed around the business and the information available.
| Reporting view | The owner’s decision |
|---|---|
| Sales and gross margin by venue | Which site or service needs attention, and what changed? |
| Food, beverage and labour costs | Did purchasing, waste, sales mix or the roster drive the result? |
| Delivery and other sales channels | Does the channel contribute enough after its direct costs? |
| Operating result against plan | Which overheads or assumptions need revisiting? |
| Short-term cash and tax commitments | What is already committed, and what can the business afford next? |
| Group and owner position | Can cash be distributed safely, and are inter-entity balances accurate? |
Work alongside your bookkeeper and venue managers
You do not need to remove a good bookkeeper to get more financial guidance. The engagement should make responsibilities easier to follow.
| Role | Agreed responsibility |
|---|---|
| Venue or operations manager | Accurate POS, stocktake, roster and operating inputs; explain changes in trading. |
| Bookkeeper or office team | Process the agreed transactions, payroll inputs and day-to-day reconciliations. |
| Acctivate | Review the accounting, prepare agreed reports and tax work, and discuss the decisions with the owner. |
| Owner or director | Approve commitments, supply context and act on agreed priorities. |
We confirm the division of work before starting. Payroll, BAS and reporting responsibilities are written into the scope so a task is not assumed to be someone else’s.
How a new venue reached $1.3M+ in annual sales
A new Brisbane venue brought us in at the very start. Elle Green CA set up the structure first, then kept the numbers current every month, so the owners could see what the venue was keeping, not just what went through the till.
Monthly sales grew almost 150% in under two years
a month, just opened
a month, loyal customer base
Sales in FY2026
Sales in the first two months of FY2027
From a brand-new venue to $1.3M+ in annual sales
- Structure set up from day one
- Monthly BAS and accounts
- Focus on what the venue keeps
- Marketing ideas beyond the books
A busy venue isn't always a profitable one
Wages, food, rent, super, GST, equipment and suppliers all run through the same bank account. A new venue grows fast, and growth on its own doesn’t mean good cash flow. The owners needed the right set-up and clear numbers before the business got big.
Foundations first, then numbers every month
Elle set up the right structure before the business took off, so nothing would need unwinding later. Monthly BAS keeps the accounts current and stops GST quietly building up. As sales grew, we kept the focus on what the venue was keeping, and pitched in on marketing and social media ideas too.
$1.3M+ a year, with profit improving
The venue went from brand new to more than $1.3 million in annual sales in under two years. Monthly sales rose from around $65,000 to more than $160,000, and profitability improved significantly on the establishment period.
Opening a venue, or already flat out?
We start the same way with cafes, restaurants and venue groups: get the structure right, keep BAS and the accounts current every month, then look at what each month leaves after wages, food and rent.
“Elle and Simon are the best accountants we have ever had. They have taken so much stress off of our plate and helped us steer our business in the right direction.”
— Hospitality business owner, Acctivate client
Client details are kept confidential. Figures are sales as published in the case study, and results are specific to this business.
CLIENT FEEDBACK
Business owners on working with Acctivate
5.0 from 200+ Google reviews. These are reviews from business owners across Acctivate’s client base. Individual experiences and service arrangements differ.
SUPPORT WHILE GROWING
★★★★★5 out of 5 stars
As a new founder, I’ve definitely had my 101 questions along the way and they’ve always been so helpful and supportive. Ale, my Client Manager is incredible! Always so prompt with her replies and happy to help with whatever I throw her way. Simon and the whole team have also been amazing to deal with! So grateful to have such a great team behind me while I navigate growing Scrub Haus!
Kassi-Lee Feeney, Scrub Haus
Google review (excerpt)
WEEKLY CHECK-INS
★★★★★5 out of 5 stars
I have had my fair share of accounts over half a decade for my business and have never found the right fit. Simon and the team at activate business accountants are the only team I have genuinely trusted when it comes to the back end of the accounting side. The weekly check ins and thorough breakdown on whats going on in my business when it comes to finances, is something I needed and appreciated. Do yourself a favour and get yourself a good accountant! This is the team you want on your side. Business isnt easy, and it pays dividends to have the right team behind you.
Matt Fitzgerald, Owner, TB Meals
Google review
XERO, PROFIT AND SALES FIGURES
★★★★★5 out of 5 stars
I met with Simon from Acctivate to review my accounting practices for my business. The session was incredibly insightful and productive. Simon gave me three key things that I could immediately review and update. Since then, I’ve implemented new practices for how I use Xero, how I manage profitability, and the way I look at my sales figures and pipeline. That one session alone has helped me get so much more clarity and confidence leading into 2026! A massive thank you to Simon. I feel like I’ve got a great supporter in my corner!
Kristy Hunter
Google review
TAX ADVICE AND PROFIT PROJECTIONS
★★★★★5 out of 5 stars
As a small business owner, having a great accountant is must! Since signing up with Acctivate we feel we can focus more on our passion and thrive, while Elle and Simon look after us. working closely with us giving tax advice, profit projections, general help with Xero and much more! They are always happy to pick up the phone and answer any questions and help where they can. We look forward to continue working closely with Acctivate and growing our businesses together.
Noam
Google review
SWITCHING ACCOUNTANTS
★★★★★5 out of 5 stars
The team at Acctivate are friendly and approachable. We made the switch from a big firm. We wanted a better relationship with our accountants and it was a breeze. Couldn’t be happier.
Zac Keune
Google review
INFORMED DECISIONS
★★★★★5 out of 5 stars
Simon and the team at Acctivate deliver insights that helps us make informed decisions. They communicate clearly and we know what to expect of them at every engagement.
Samuel Longfield
Google review
Meet the accountants behind the advice
Your records, reporting and tax planning need clear ownership. We agree who manages the day-to-day work, who reviews it and who meets with you to discuss the numbers.
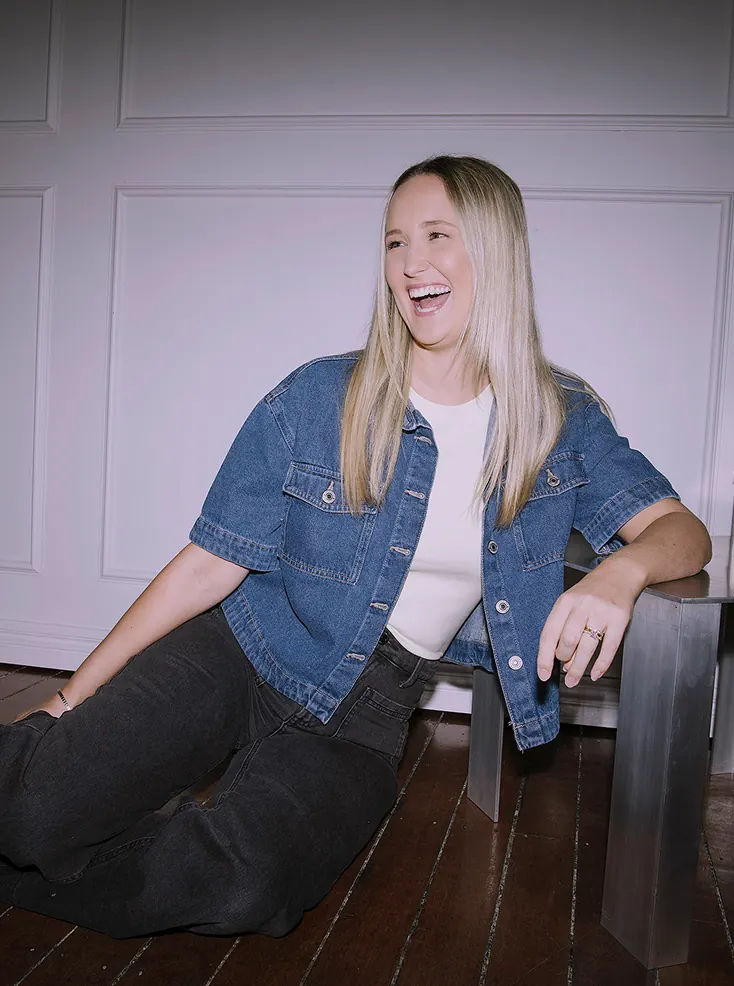
Elle Green CA
Director and Co-Founder
Elle is a Chartered Accountant and Registered Tax Agent who specialises in small business taxation and cash flow management. She won Accounting Consultant of the Year at the Women in Finance Awards 2025.
Meet Elle
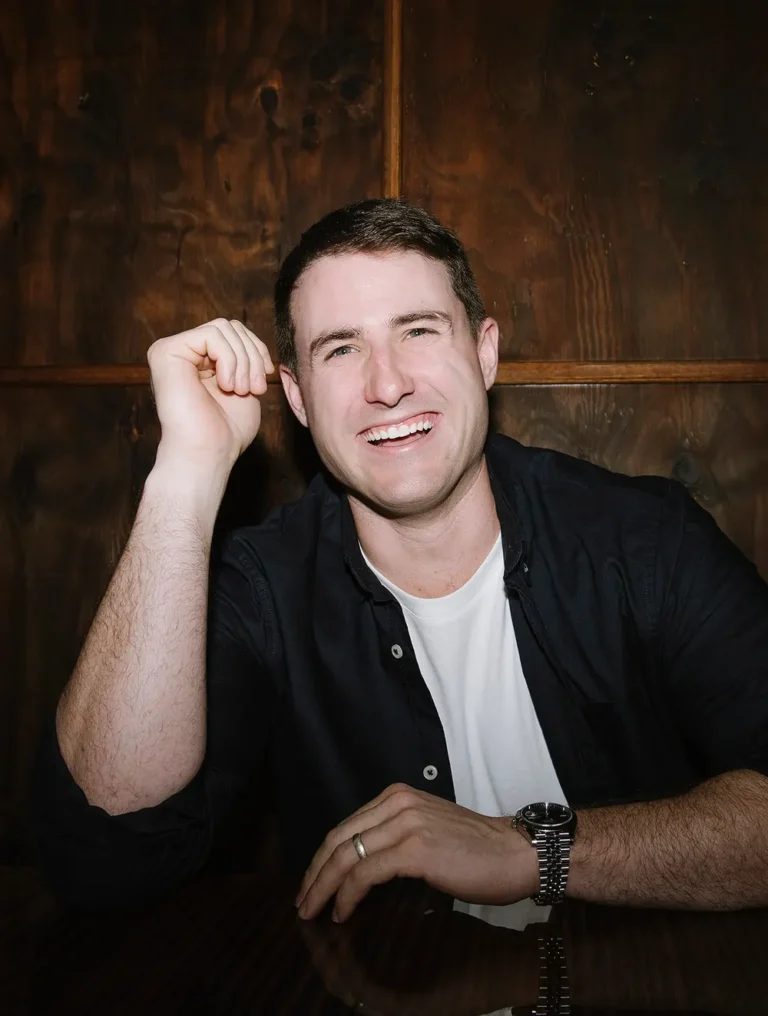
Simon Burke CA
Director and Co-Founder
Simon is a Chartered Accountant working across accounting and business advisory. He helps owners assess cash flow, business structures and operating decisions as their business becomes more complex.
Meet Simon
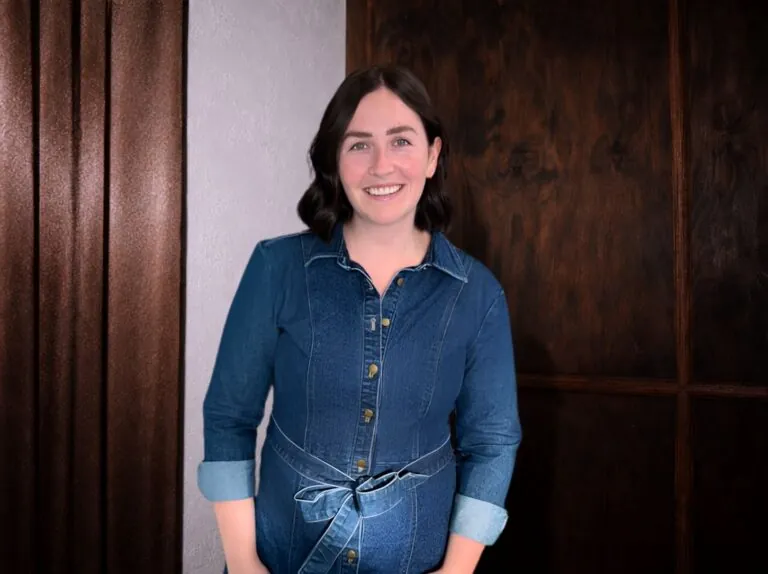
Chloe Sullings CPA
Business Specialist
Chloe is a CPA whose experience runs from boutique practices to top 100 firms. She breaks complex accounting information down so owners understand it and know which questions it raises for the business.
Meet the team
Why an owner chooses Acctivate for hospitality accounting
The value is in the working relationship: reliable records, clear responsibilities and conversations that happen while the owner still has choices.
Named people behind the advice
CA directors Elle Green and Simon Burke lead the firm. Your engagement identifies the people responsible for the work and the review conversation.
Experience you can examine
The published hospitality case explains the business situation and the accounting work. You can assess that evidence alongside client reviews and the team’s qualifications.
Reporting connected to operations
Venue, stock, staffing and settlement information are considered together. The aim is to explain the financial result in terms the owner recognises.
Scope agreed before the work starts
We agree compliance, reporting, advisory, bookkeeping and payroll responsibilities, including review frequency and any catch-up work.
What working together looks like
We start with the venue you run today and the financial question prompting the conversation.
| Stage | What happens | Your part |
|---|---|---|
| Understand | Discuss the venue, owners, staff, systems and current concern. | Explain what is changing and what you need to decide. |
| Review | Assess accounts, BAS, POS and reporting arrangements. | Provide the relevant records and access after engagement. |
| Agree | Set the scope, responsibilities, reporting frequency and fee. | Confirm the service and the people who supply the inputs. |
| Set up | Coordinate the handover and resolve priority accounting gaps. | Keep agreed records current and respond to queries. |
| Review and act | Discuss performance, cash, tax and upcoming commitments. | Make decisions with a clearer view of the financial effect. |
An agreed scope and monthly fee
The fee reflects the number of venues and entities, transaction and payroll volume, condition of the records, reporting frequency and advisory scope. We agree the work and fee in writing, including any separate catch-up or project work. A change in scope is discussed before additional work proceeds.
Changing accountants during the year
You can start the conversation before 30 June. Once engaged, we request the records needed from your existing accountant, check outstanding lodgements and agree responsibilities with your bookkeeper or finance team. Any catch-up work is scoped before it begins.
Hospitality accounting wherever your venues operate
We work with Australian business owners through secure access to records, online meetings and agreed reporting routines. A group operating across state borders also needs the relevant payroll tax, workers’ compensation and licensing questions considered. We establish the accounting scope and involve the appropriate specialist where required. You do not need a local office visit to have a regular conversation about your numbers.
Questions hospitality owners ask before engaging an accountant
Do you work with restaurants, cafes and hospitality groups?
Our service is designed for established food-service and venue businesses that need ongoing accounting, tax and financial oversight. Tell us about the operation, number of sites, staff and systems so we can confirm the scope and fit.
Why is my venue busy but not profitable?
Sales can increase while food, labour, waste, delivery fees and fixed costs absorb the extra revenue. Start with consistently prepared accounts, then examine the sales mix and operating information that explain the change. See the worked venue example.
What is prime cost, and what percentage should it be?
Prime cost generally combines cost of goods and labour. The definitions need to be consistent. There is no single percentage that establishes a suitable result for every venue; rent, service model, sales mix and other commitments also matter.
Can you help us understand the cost of our roster?
We can assess the financial effect using accurate payroll inputs, trading patterns and the proposed staffing arrangement. Award coverage and employment interpretation require appropriate expertise. Payroll processing and review responsibilities are agreed in the scope.
Why do delivery payouts differ from our recorded sales?
Platforms may deduct fees, refunds or other adjustments and pay on a different timetable. Reconcile the transaction and settlement records rather than recording the deposit as the entire sale. See the accounting workflow.
Can you compare the results of our venues?
Yes, where the records support reliable site reporting. We establish consistent sales and cost categories, identify shared costs and reconcile transactions between entities before drawing conclusions about each venue.
Can you assess whether we can afford a second venue?
We can model the financial commitment and its effect on the existing business. That includes deposits, fit-out, equipment, staffing, opening stock and the ramp-up period, alongside a slower trading case. Legal and funding advice are separate specialist roles.
Do we have to move to monthly BAS?
Not automatically. The appropriate BAS arrangements depend on your obligations and circumstances. Monthly management reporting is a separate process that still requires reconciliations, stock and wage information and relevant adjustments.
Can you work with our existing bookkeeper?
Yes. We agree who handles transactions, payroll inputs, reconciliations, reporting and lodgements so the owner, venue team and bookkeeper know what is expected.
Which POS and accounting software do you support?
We work with Xero and review how your POS, merchant, delivery and payroll information reaches the accounts. We confirm compatibility and responsibilities before agreeing any system or integration work; a direct connection is not assumed.
How much does a hospitality accountant cost?
The fee depends on venue and entity numbers, payroll and transaction volume, record quality, reporting frequency and advisory work. We agree the scope and fee before starting. See how the engagement works.
Can we work with Acctivate outside Brisbane?
Yes. Records and meetings can be handled remotely. We identify state-specific obligations relevant to the engagement without treating the business as though it has an office in every city.
Can we change accountants during the year?
Yes. You do not need to wait for the financial year to end. We assess outstanding work, coordinate the record handover once engaged and agree a practical starting point.
What should I bring to the first conversation?
Your approximate turnover, number of venues and staff, entity structure, current systems and the issue prompting the enquiry. Recent accounts or BAS can help, but the first conversation can start with an explanation of the business.
LET'S TALK
Talk through the numbers behind your venue
Tell us how the venue operates, what is changing and where you need a clearer financial picture. We will discuss the work your business needs and whether Acctivate is the right fit.
★★★★★5 out of 5 stars
Led by Chartered Accountants Elle Green and Simon Burke.
We review every enquiry and contact you to discuss your business and the support it needs.
We use your details only to respond to your enquiry. Privacy policy
This page is general information only and isn’t advice. It doesn’t take your circumstances into account. Speak with us before acting on it.
ACCTIVATE PTY LTD · ABN 63 677 493 882 · Level 5/ 269 Wickham St, Fortitude Valley · (07) 3185 5303
